
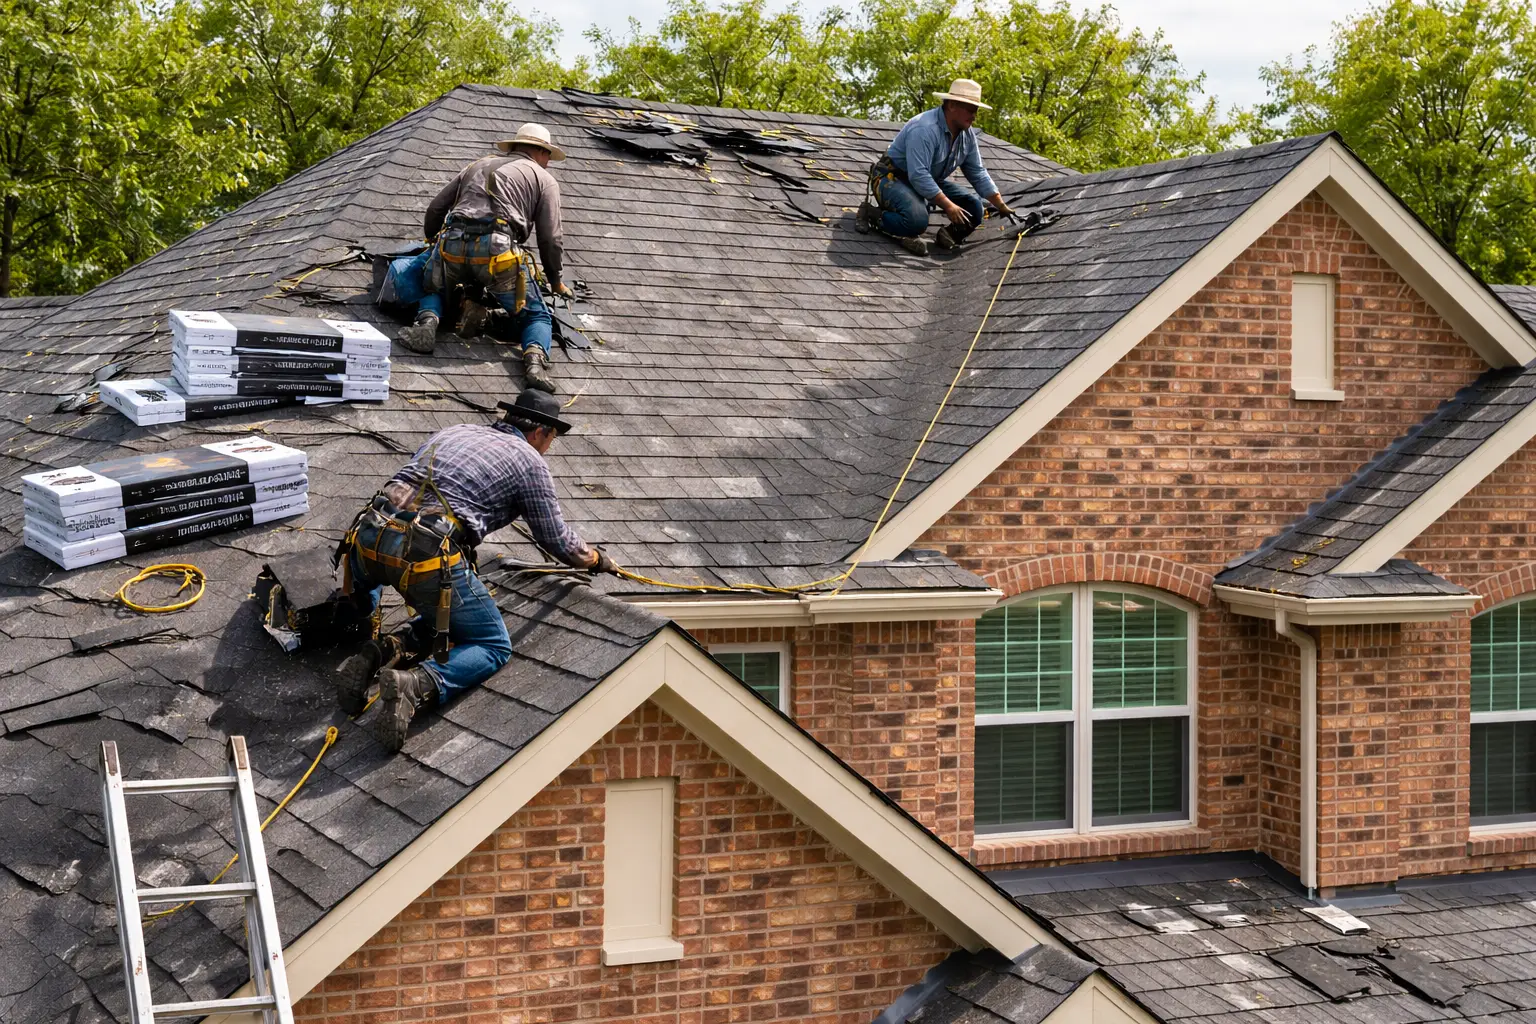
A denial letter or a lowball estimate isn’t the end of your claim — in Texas, it’s often just the opening position. Here’s what your options actually are, and how supplements, re-inspections, and the appraisal process work.
Hail Damage Claim Denied: Your Options
In rough order: (1) Request the denial in writing with specific reasons — you’re entitled to that. (2) Get an independent professional re-inspection; many denials rest on a rushed 20-minute adjuster visit, and thorough photo documentation of functional damage is grounds to request a re-inspection. (3) File a supplement or dispute backed by the new evidence. (4) Invoke the appraisal clause in your policy — a formal dispute-resolution process. (5) File a complaint with the Texas Department of Insurance, or consult a public adjuster or policyholder attorney for bad-faith situations. APGC’s BEI-credentialed inspectors produce the kind of measured, documented evidence that gets legitimate claims a second look — and the second opinion is free.
Insurance Underestimating the Damage: What to Do
Underestimating usually takes three forms: missed damage (slopes, gutters, siding, fencing not scoped), lowball unit pricing no legitimate contractor can build at, or repair scopes where replacement is warranted. The remedy is the supplement process: your contractor documents the discrepancy — photos, measurements, code requirements, current pricing — and submits a revised scope. This is routine; carriers process supplements every day, and storm claims frequently end up meaningfully higher than the first estimate once properly scoped. APGC handles supplements on every insurance job at no extra charge.
Insurance Approved a Partial Repair — Should You Push for More?
Sometimes a partial approval is right; sometimes it’s the opening offer. Ask: does the approved scope address all the documented damage, or just what the adjuster saw that day? Will repaired slopes match the rest of the roof? Is there unscoped damage to gutters, siding, screens, or fencing? If the scope genuinely covers the damage, take the repair — a good partial repair on a healthy roof is a fine outcome. If our documentation shows more, we prepare a supplement with evidence. Supplements are normal, not adversarial.
What Is the 25% Rule for Roof Replacement?
When repairs would affect a substantial portion of the roof (often cited around 25%), matching and code considerations frequently push toward full replacement rather than patching. Texas expects repaired sections to reasonably match the rest of the roof — and discontinued shingle colors and profiles often make true matching impossible. When APGC finds widespread damage, we document the matching issue itself as claim evidence; it’s one of the most common places an experienced contractor changes a claim’s outcome.
Hail Hit the Gutters, Siding AND Roof — One Claim?
Yes — one storm, one claim, one deductible. Your policy covers all storm damage from that event: roof, gutters, siding, screens, garage doors, fences, painted surfaces, and interior water damage if it got in. The mistake is filing a “roof claim” when you actually have a property claim. APGC inspects the entire property, and as a full general contractor — not just a roofer — we can complete all of it: roofing, gutters, siding, painting, fencing, and interior build-back. One claim, one accountable team.
Get a Free, Photo-Documented Roof Inspection
American Prime General Construction is a veteran-led, BBB A+ accredited roofing contractor based in Richardson, serving the entire DFW metroplex. If hail has hit your neighborhood, our BEI-credentialed inspectors will document exactly what the storm did to your home — free, with no obligation. Call or text our 24/7 storm line at (469) 888-8326 or request your free inspection online.
This article is general information for Texas homeowners, not legal or insurance advice. American Prime General Construction is a general contractor — not a public adjuster, insurance agent, or law firm — and does not adjust, negotiate, or settle insurance claims on behalf of policyholders. For advice about your specific policy or claim, contact your insurance agent or carrier, the Texas Department of Insurance (tdi.texas.gov, 1-800-252-3439), a licensed public adjuster, or an attorney.